Wall Street Sets $254 Target for SK Hynix (SKHY) as Memory Chip Demand Tightens
Key Takeaways
- SK Hynix shares declined 2% in Nasdaq premarket and 4% during Seoul trading hours.
- Third-quarter 2026 earnings are scheduled for release on October 27.
- Consensus among analysts remains Strong Buy, with a $254.70 average target suggesting 30%-plus gains.
- Barclays maintains a $300 price objective, pointing to potential 50% appreciation driven by shareholder distributions and production expansion.
- Samsung’s simultaneous decline contributed to the KOSPI index falling under 7,000.
Shares of SK Hynix retreated over 2% in Nasdaq premarket activity on Monday. The Seoul-listed stock experienced a steeper decline of nearly 4% during the same session.
The pullback arrives just weeks ahead of the company’s scheduled third-quarter 2026 financial results on October 27. Market participants appear cautious as the reporting date approaches.
Two key factors are weighing on sentiment. A stronger Korean won is eroding the value of foreign revenue when converted back, while the company confronts higher bonus obligations linked to its AI-driven profitability gains over the previous year.
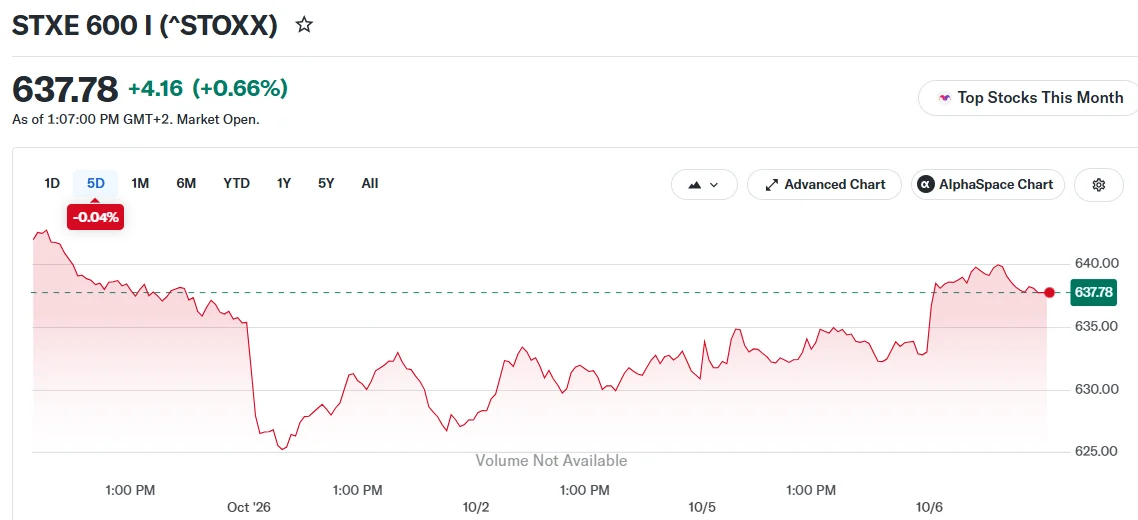
Samsung Electronics experienced similar downward momentum, shedding approximately 2% in Seoul before its preliminary third-quarter figures due later this week. The KOSPI benchmark dropped beneath the 7,000 threshold after foreign investors withdrew a net ₩1.76 trillion, equivalent to $1.30 billion, from Korean equities.
SK Hynix manufactures memory semiconductors, including DRAM and NAND varieties, which serve AI infrastructure, data centers, personal computers, and mobile devices.
Wall Street Conviction Holds Firm Amid Price Weakness
The recent decline hasn’t shaken analyst confidence. Barclays’ Simon Coles reaffirmed his Buy stance with a $300 valuation, representing potential appreciation exceeding 50% from present levels.
Coles anticipates SK Hynix will distribute roughly 15% of its total market capitalization back to investors. He also sees runway for capacity expansion and pursuit of emerging growth avenues.
The analyst identified the forthcoming quarterly report as a critical near-term catalyst. Investors are likely to gain deeper insight into share repurchase strategies and capital allocation priorities during that release.
Coles further argues SK Hynix is strategically positioned to benefit from constrained memory supply relative to demand. He projects this dynamic will support elevated average selling prices, even if major customers reduce memory content per unit to navigate supply constraints.
Wolfe Research’s Chris Caso shares the optimistic outlook. He lifted his price objective to $250 from $200 while maintaining his Buy recommendation.
Caso’s revised forecast incorporates sustained pricing momentum across memory markets. He projects demand will exceed available supply through 2028 at minimum.
This supply-demand imbalance, according to Caso, should enable additional price hikes going forward. He calculates that SK Hynix could generate sufficient free cash flow during 2026 and 2027 to repurchase stock equivalent to approximately 32% of its current market capitalization.
Broader Analyst Sentiment and Industry Context
The Street’s consensus view on SKHY stock remains Strong Buy, supported by 11 Buy ratings issued over the last three months. The $254.70 mean price target suggests potential gains exceeding 30% from today’s trading levels.
Samsung’s upcoming disclosure is projected to reveal operating income surpassing 100 trillion won, or $74.05 billion, which would establish a new company record.
SK Hynix is similarly anticipated to deliver robust year-over-year expansion when it unveils results later this month. The upcoming quarter followed a period that included a substantial ADR placement.
Competitor Micron released solid quarterly results last week, indicating AI-related demand remained healthy through at least September. Micron’s management also projected memory supply tightness would persist for another year minimum.
This industry backdrop creates a favorable setup for both Samsung and SK Hynix entering their respective reporting periods. However, recent accounts of data center project postponements in the United States have introduced some uncertainty regarding the trajectory of AI chip consumption.
At present, both equities are trading at reduced valuations as market participants await concrete financial data rather than projections.
The post Wall Street Sets $254 Target for SK Hynix (SKHY) as Memory Chip Demand Tightens appeared first on Blockonomi.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
Comments (0)